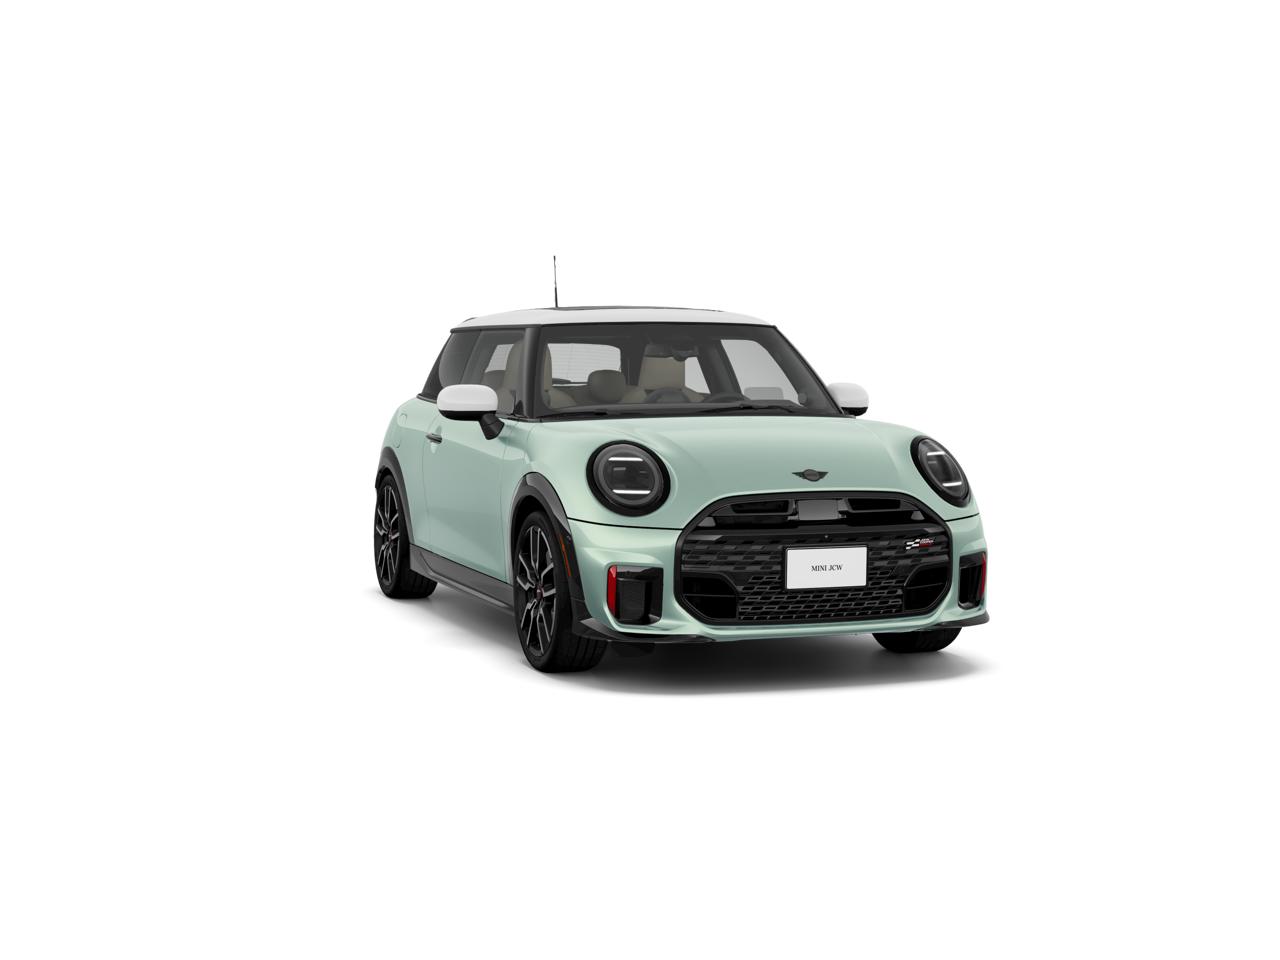
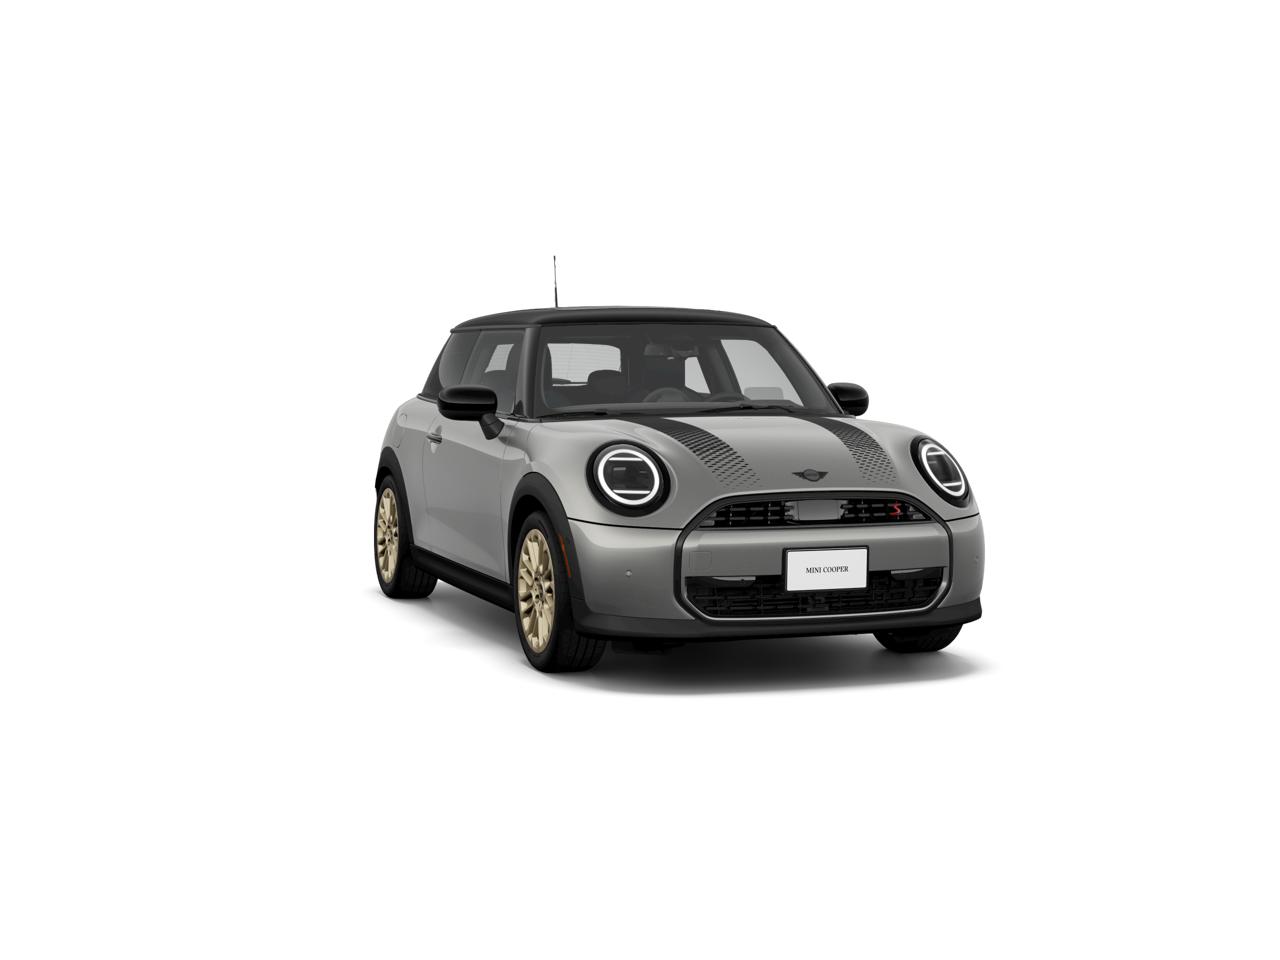
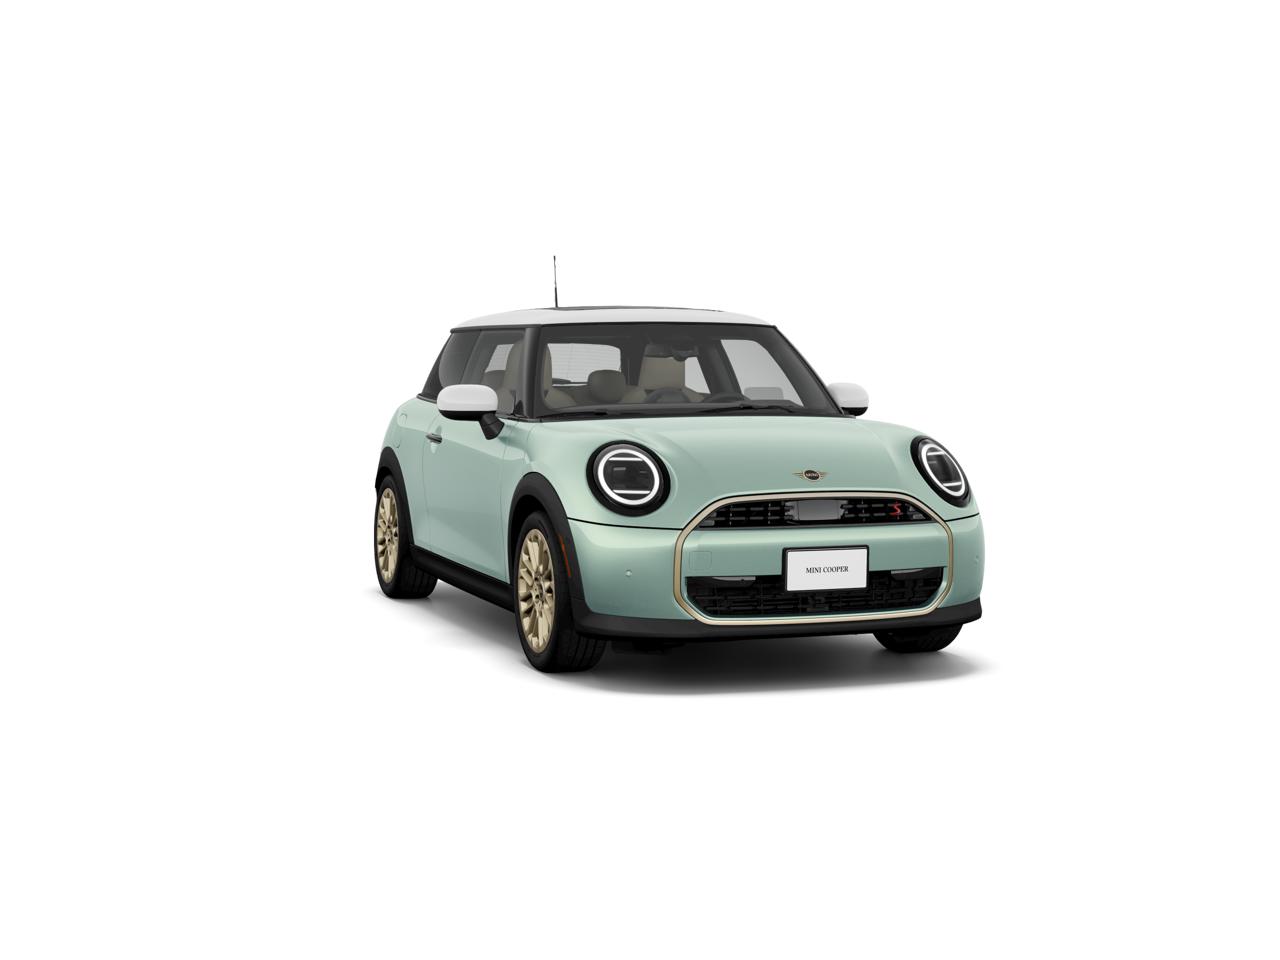
New MINI 2 Door Lease Deals in Woodbury, NY.
Frequently Asked Questions About New MINI 2 Door Lease Deals in Woodbury, NY
Can I lease a car if I have very little credit history?
Often yes, though a lender may ask for proof of income, extra documents or a co-signer. Starting with a credit review shows which of those apply before you settle on a car.
What is a co-signer really promising on a lease?
A co-signer takes on legal responsibility for the lease if the main driver stops paying. That obligation usually lasts for the entire term, so it deserves a careful conversation within the family first.
How much insurance does a leased car need?
The leasing company sets minimum coverage levels, which typically exceed what the state requires and include collision and comprehensive protection. Your agent can quote the exact levels once you know the car and the lender.
What should I bring when I ask for a lease quote?
Bring your driver license, recent proof of income and your insurance agent's contact details. Knowing which MINI you want and roughly how much you drive each year speeds everything up.
How do I choose between a lower and a higher mileage allowance?
Look at how you actually drive across a typical season, then add a cushion for trips you already know are coming. Buying extra miles at signing often costs less than paying overage at turn-in, although unused miles are generally not refunded.
Have Additional Questions?
Nobody expects a first-time lessee to know the vocabulary already.
Questions about approval, co-signers or insurance are the everyday business of the finance office, and none of them is too basic to raise.
Reach out to Habberstad MINI by message or phone and start wherever your uncertainty begins.
A First New Car, Arranged as a Lease
Many people shopping for a MINI 2 Door in Woodbury have never had a brand-new car in their own name. A lease is often how that first step happens, since it puts a new car in your driveway for a set stretch without the commitment of owning it outright. The paperwork looks unfamiliar the first time, yet each piece has a plain purpose once someone walks you through it.
On a lease you cover the share of the car's value used up while you drive it, plus the leasing company's costs, and then hand it back or decide what comes next. You never hold the title during the term, which is why the lender asks a few questions a cash buyer would never hear. Knowing those questions ahead of time takes most of the nerves out of a first visit.
- A lease application that reads much like an apartment rental form, asking about income, employment and the addresses where you have lived recently
- A signed agreement spelling out who owns the car, what shape it should come back in and which costs belong to you while it is parked at home
- A turn-in appointment at the close of the term, when the car gets looked over and you pick between returning it, buying it or leasing another
None of this requires a long credit history or a finance background. It requires a little preparation and a willingness to keep asking until every line of the agreement makes sense to you. Most first-time lessees in Woodbury find the whole process fits into one unhurried sitting once their documents are gathered.
First-time lessees tend to ask the most useful questions in the room. Bring every one of them along when you sit down with Habberstad MINI.
Credit Approval, and When a Co-Signer Steps In
Approval on a lease depends on the leasing company reviewing your credit file, your income and how steady your work has been. A thin file is common for recent graduates and younger drivers in Woodbury, and it does not automatically mean a no. It may simply mean the lender wants more documentation or a second person on the application.
A co-signer, often a parent or a spouse with established credit, agrees to be responsible for the lease if the primary driver cannot keep up. That is a serious promise, so everyone involved should read the agreement before anyone signs. Some first-time lessees qualify on their own, and an early credit review shows which situation applies to you.
- Recent pay stubs or an offer letter from a new employer, which help a lender see steady income when your credit report is still short on history
- A co-signer who understands they share responsibility for the whole agreement, not merely a vague promise to help out if a bill runs late
- A look at your own credit report before applying, so an old error or an unfamiliar account can be cleared up ahead of the paperwork
Our finance team places applications with several lenders, and approval standards differ among them. Talking openly about your situation lets them steer the application toward a lender whose requirements you can actually meet. If the timing is not right yet, they will explain what would strengthen the application on a second try.
Credit questions feel personal, and they are handled that way. Share what the application needs, and ask why each item is requested.
Insuring a Car the Leasing Company Owns
Because the leasing company keeps ownership, it sets minimum insurance coverage that you carry for the whole term. Those minimums usually sit above the bare legal floor, and they include protection for damage to the car itself. A first-time driver who has only been listed on a family policy should call an agent early, since that quote shapes what leasing will really cost.
Many lessees also add gap coverage, which fills the space between an insurer's payout after a total loss and the balance still owed on the lease. Some lease agreements include it and others do not, so ask which applies to the car you are considering. Your agent can explain how it fits with the rest of your policy.
- A quote from your insurance agent on the exact MINI 2 Door you plan to lease, requested well before the day you expect to sign
- Proof of coverage naming the leasing company as loss payee, which the finance office needs in hand before the car can go home with you
- A clear answer on gap coverage, either built into the lease agreement or added through your own insurer, so no stretch of the term goes unprotected
A daily drive along Jericho Turnpike, with its stop-and-go traffic and packed shopping lots, is exactly where small dents and fender scrapes happen. Carrying the right coverage turns a minor bump into a claim and a repair, not an unpleasant surprise at turn-in.
Ask your agent about deductibles as well as premiums. A lower deductible can make small repairs easier to absorb during the lease.
What the 2 Door Is Like for a Newer Driver
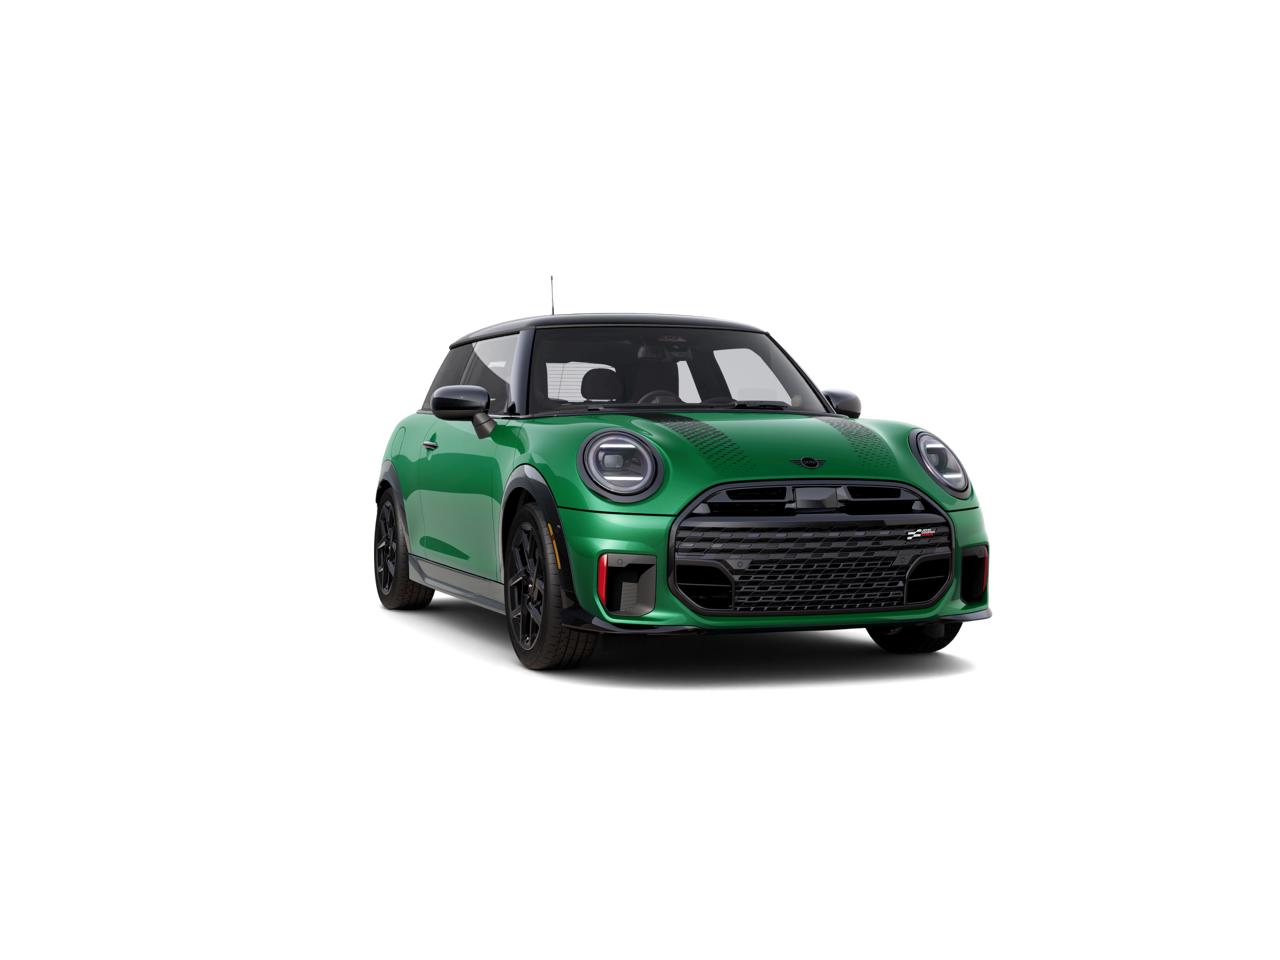
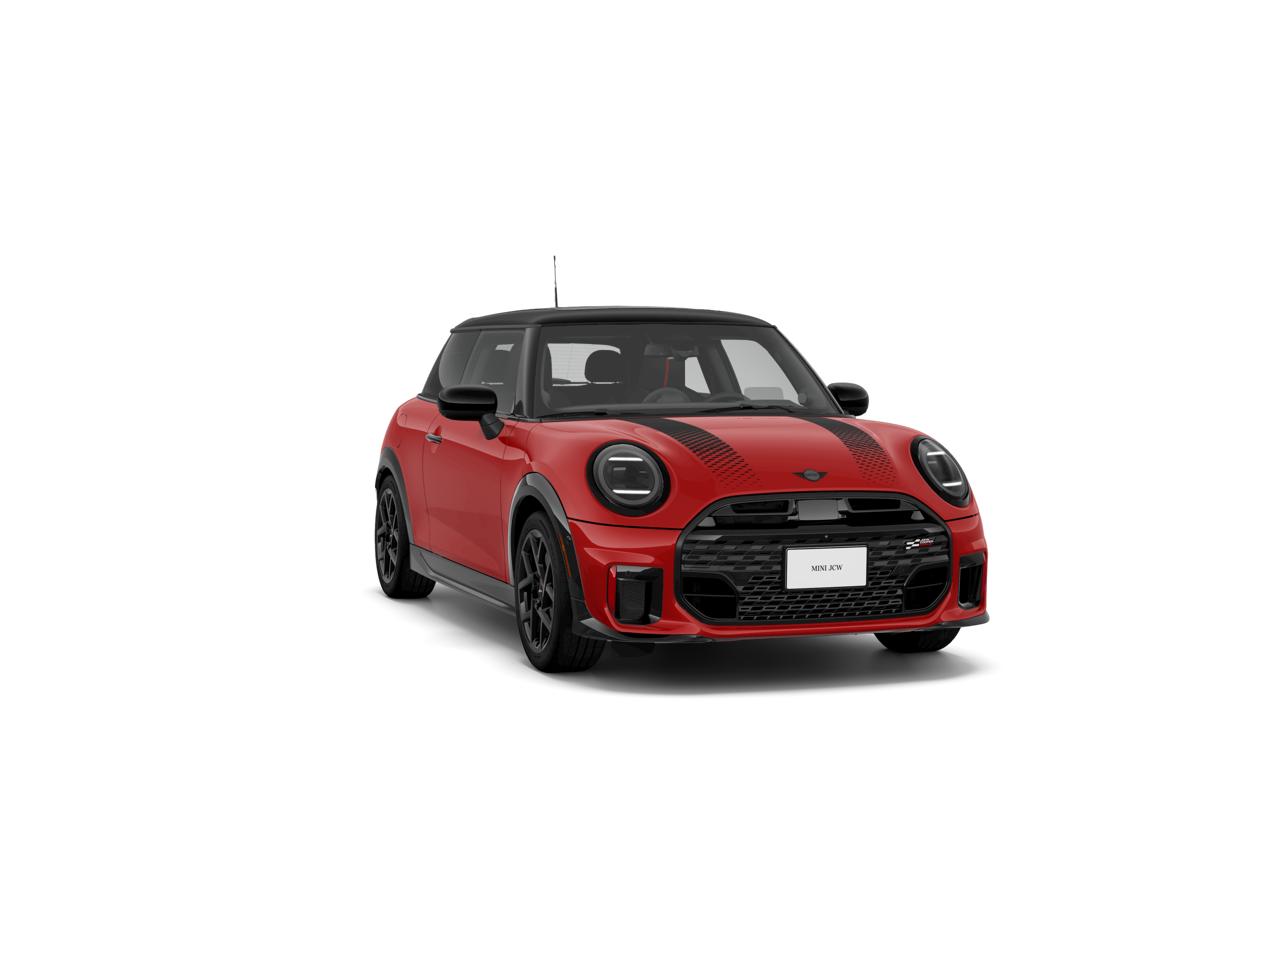
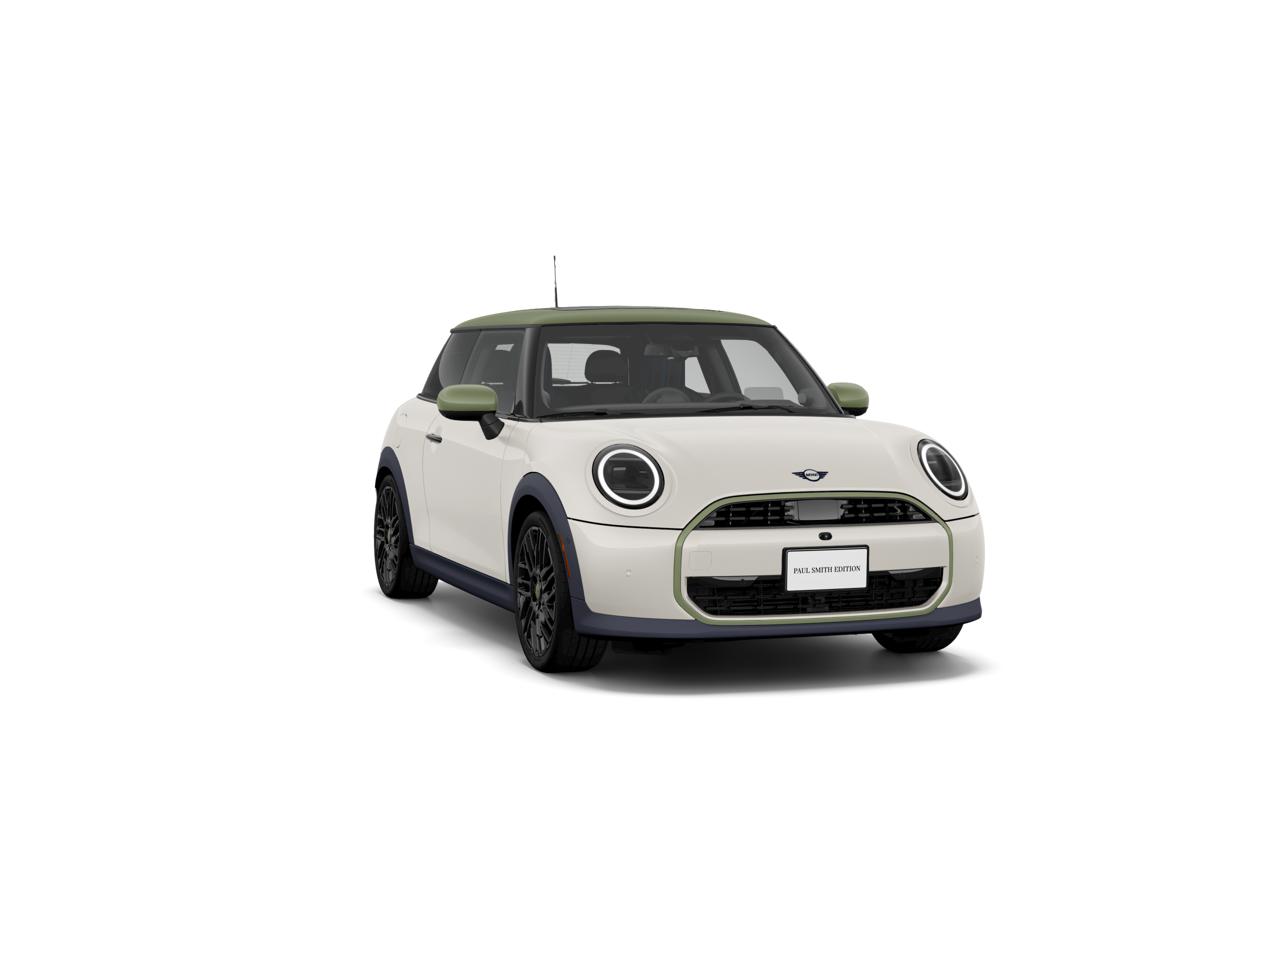
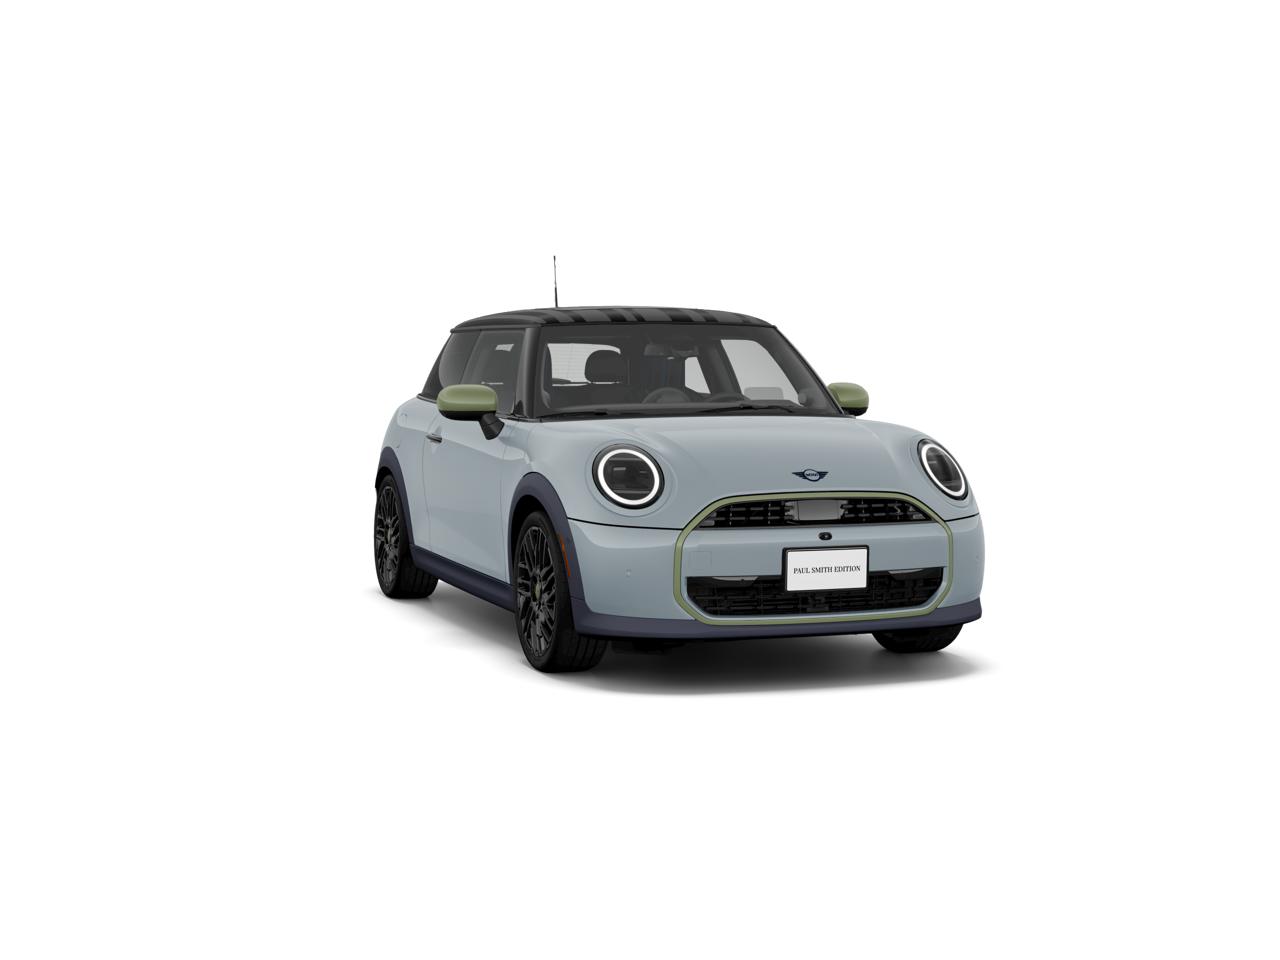
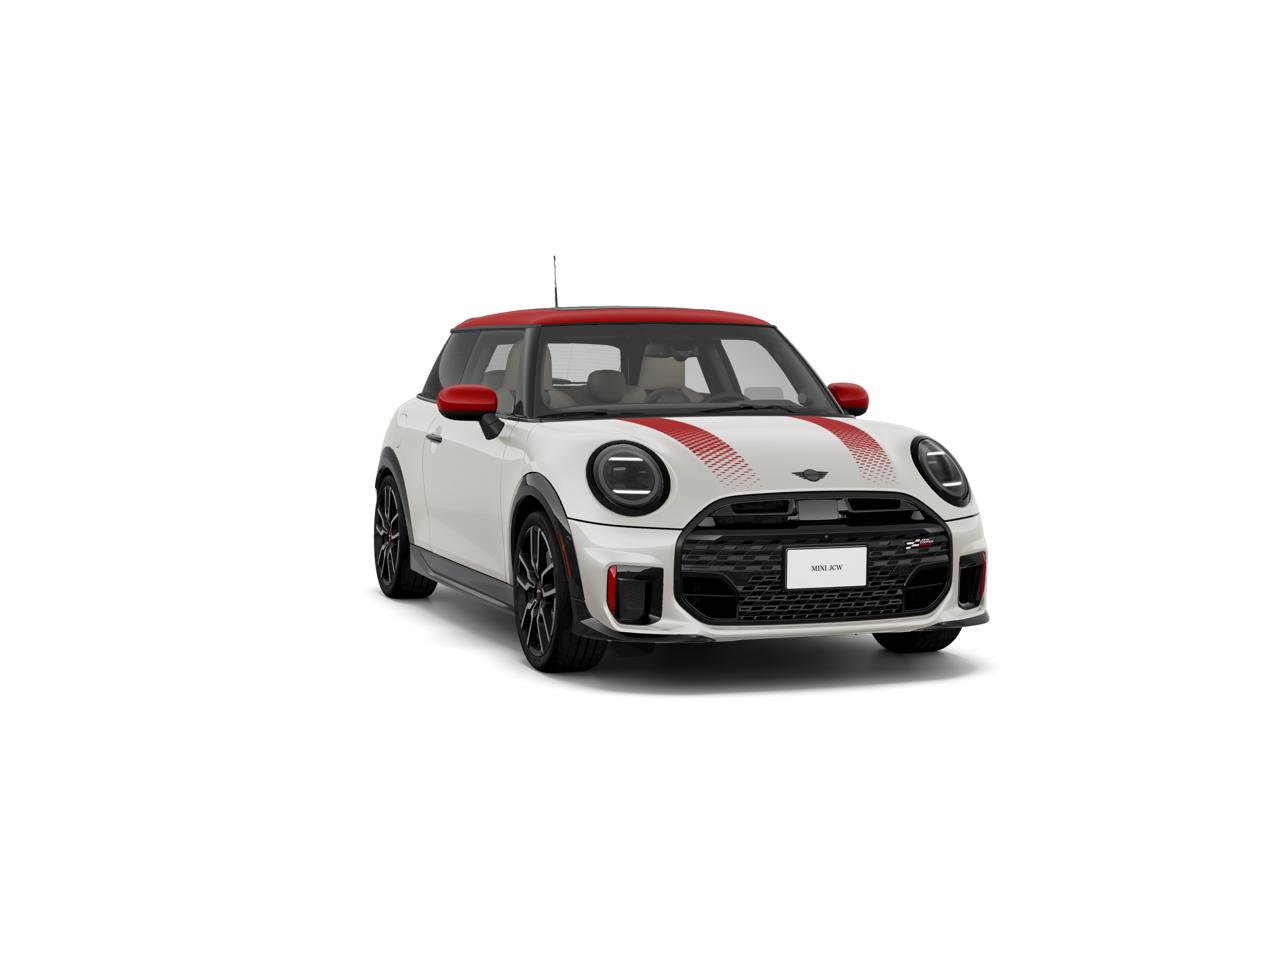
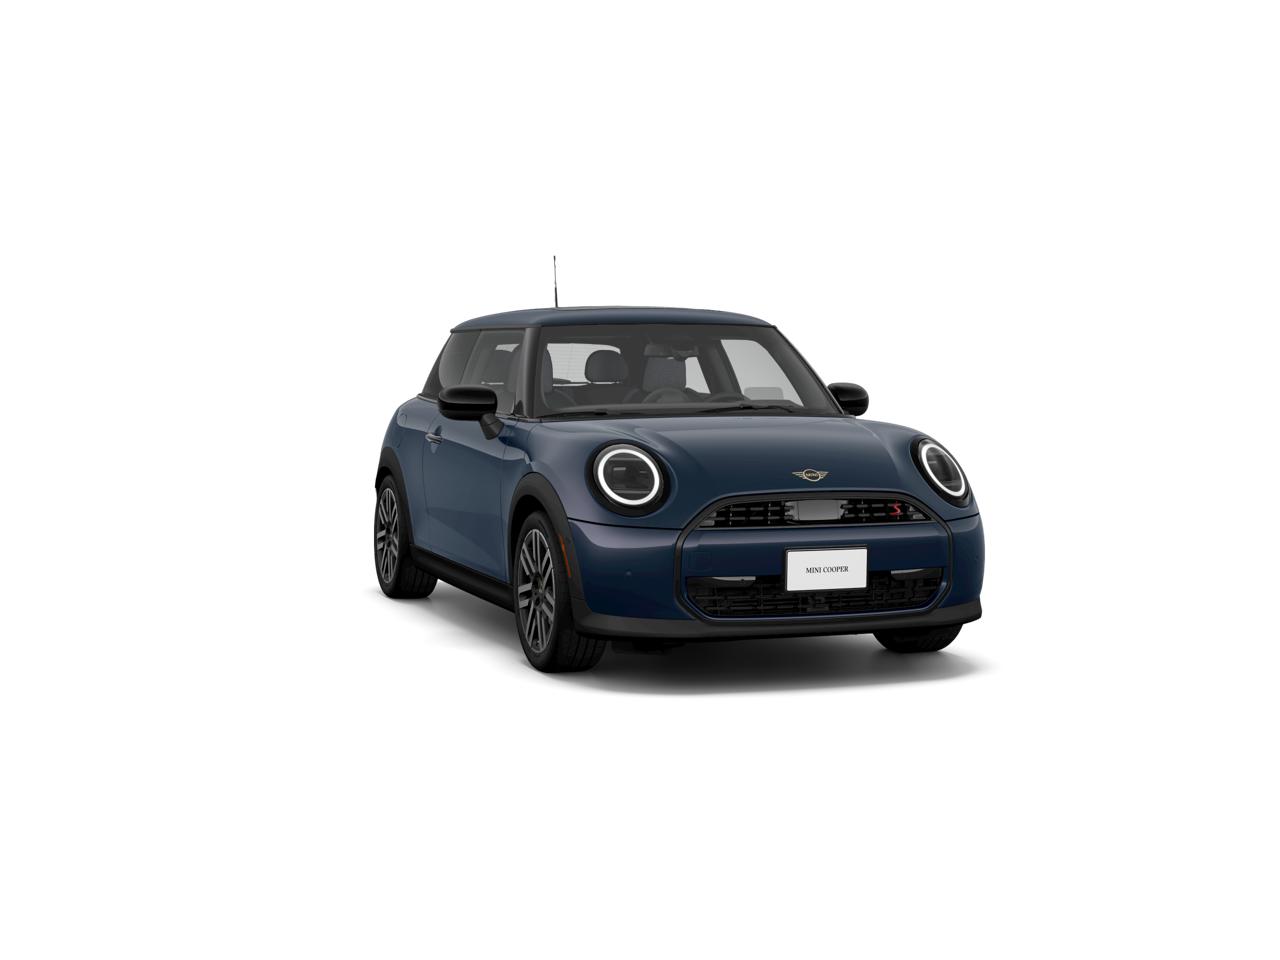
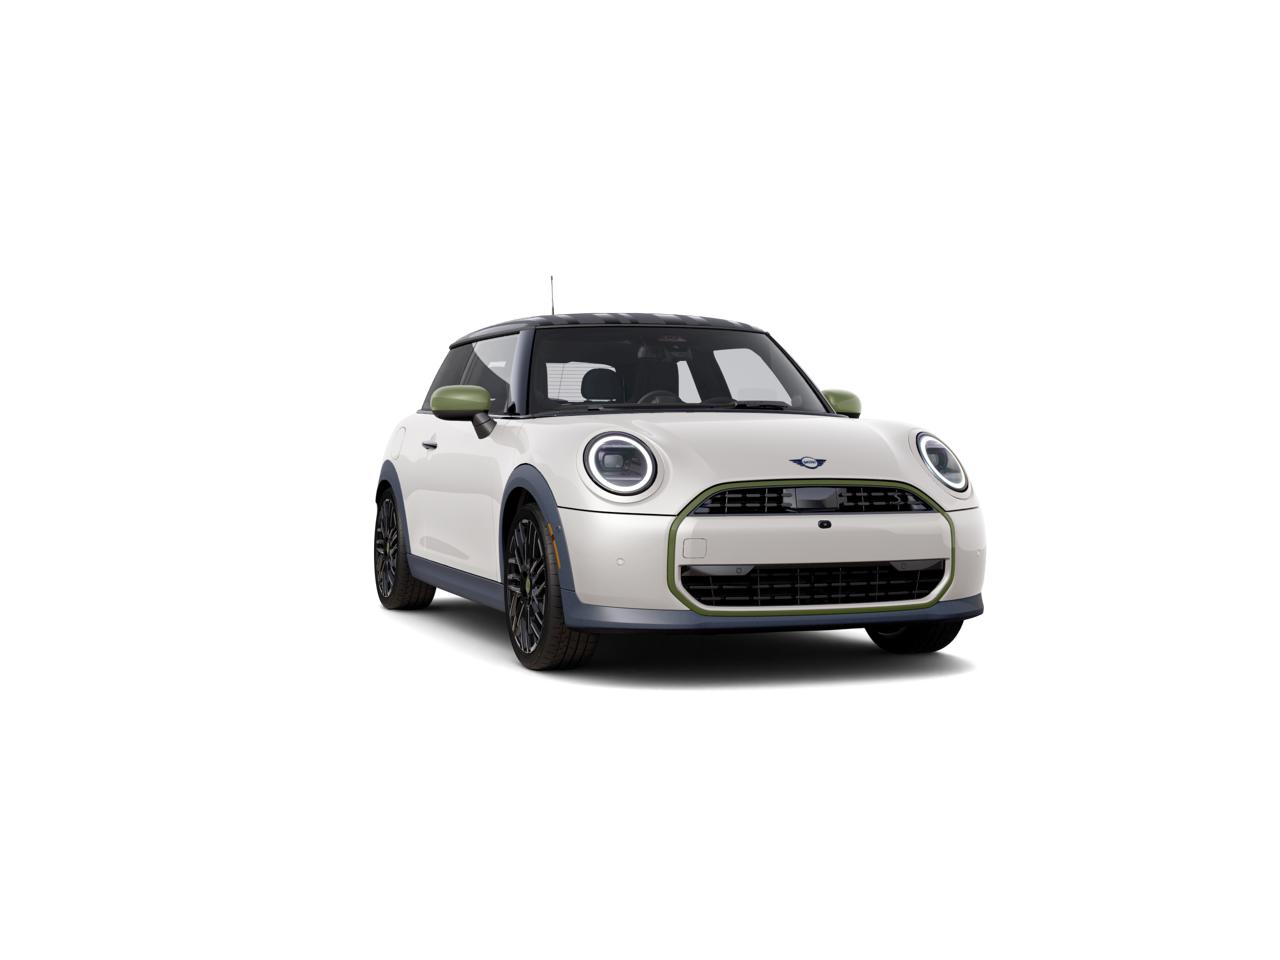
The MINI 2 Door is short, quick to react and easy to see out of, which makes it a comfortable first new car for someone still building confidence. Squeezing into a spot at a crowded Plainview shopping center feels manageable in a car this compact. The go-kart feel MINI is known for shows up in every corner, even at ordinary speeds.
Its small rear seat and hatch suit a single driver or a couple far better than a family, and that is part of its appeal. Friends fit in back for short hops, while groceries, a gym bag or a weekend duffel slide under the hatch without fuss. A lease matches that stage of life well, because the next car can change when your needs do.
- A tight turning circle that makes U-turns and busy lots in Syosset less stressful for a driver still learning to judge narrow gaps
- Tall windows and a short hood that help a new driver sense the corners of the car when easing into a parallel spot
- A rear hatch sized for groceries and a gym bag, with the back seat folding down whenever a bigger errand comes along
Plan a test drive that covers a quiet residential street and a busier stretch near Plainview. You will know quickly whether the quick steering feels playful or twitchy to you. Bring along whoever usually rides with you, since their opinion of the back seat matters too.
A first car should feel natural within a few minutes. If it does not, the team can suggest another MINI body style to try.
How Many Miles to Plan For, and Where to Start
A yearly mileage allowance is written into every lease, and setting it is one of the few decisions that belongs entirely to you. A first-time lessee with a short commute might pick a lower allowance, while someone crossing the county for work or school may want a higher one. Going over the allowance costs money at turn-in, so a candid estimate matters more than a hopeful one.
To build a live quote, Habberstad MINI needs the specific car you want, whether you prefer a shorter or longer term, your yearly mileage estimate and permission to check your credit. With those details, the finance team can show what the lease looks like today, not a generic advertised figure. Quotes move as lender programs and inventory move, so ask for one close to when you plan to decide.
- A realistic look at your weekly driving, including trips home to family or visits to friends upstate, before settling on a yearly mileage allowance
- Routine maintenance handled by factory-trained technicians, with reminders from the car itself whenever a service visit comes due during the lease
- A walkthrough of the paths at lease end, returning the car, buying it or leasing a new MINI, so the finish line never feels unfamiliar
A new car also begins a new service relationship. Bringing the MINI back for scheduled maintenance keeps its record complete, which helps if you later decide to buy it once the lease wraps up. Technicians also spot small issues early, when a fix is simple and nowhere near turn-in.
Keep every service receipt together in one folder. It makes a turn-in or a buyout simpler when the term closes.
Your first lease should feel clear before it feels exciting. Ask Habberstad MINI to price the MINI 2 Door you want in Woodbury as things stand today, and bring every question you have about approval and insurance along with you.